- Film & Animation
- Music
- Comedy
- Sports
- Travel & Events
- Gaming
- People & Blogs
- Comedy
- Entertainment
- News & Politics
- How-to & Style
- Non-profits & Activism
- Autos & Vehicles
- Pets & Animals
- Education
- Science & Technology
- Church
- Gospel
- Sermons & Bible Study
- Business & Finance
- Health & Wellness
- Food & Cooking
- Kids & Family
- Documentaries
- Lifestyle
- Other
The Kenya Bankers Association (KBA) has called for a major overhaul of Kenya's lending model in a move aimed at improving access to credit for Kenyans. Breaking It Down Speaking during the East Africa Banking School Conference (EABSC) 2026 on Tuesday, July 14, KBA Chairman Paul Russo called on lenders to stop relying primarily on collateral when deciding whether to approve loans. According to Russo, collateral should remain an important safegu
07/14/26 • 37 Views
The Kenya Bankers Association (KBA) has called for a major overhaul of Kenya's lending model in a move aimed at improving access to credit for Kenyans.
🇰🇪 Breaking It Down
Speaking during the East Africa Banking School Conference (EABSC) 2026 on Tuesday, July 14, KBA Chairman Paul Russo called on lenders to stop relying primarily on collateral when deciding whether to approve loans.
According to Russo, collateral should remain an important safeguard in lending, but should no longer be the primary factor used to assess borrowers, as it locks millions of small businesses out of formal credit.
"While collateral will always have an important place in lending, it should not become the main decision tool to determine lending," Russo stated.
📌 What You Need to Know
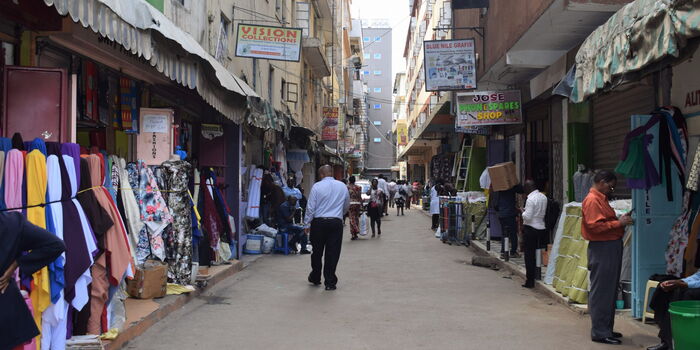
He noted that Kenya's continued reliance on collateral remains one of the biggest barriers to accessing credit, particularly for micro, small, and medium-sized enterprises (MSMEs), which form the backbone of the country's economy.
He cited data from the Kenya National Bureau of Statistics (KNBS) that shows the country has more than 7.4 million MSMEs, yet fewer than 20 per cent can access formal credit.
As a result, the vast majority are forced to rely on informal financing to fund their operations and expansion.
"According to KNBS, Kenya has over 7.4 million MSMEs, yet below 20 per cent can access common credit, leading the vast mnajority dependant on informal sources of finance", he added.
In his proposal, Russo argued that banks and policymakers should focus on strengthening alternative credit assessment models that evaluate businesses based on their ability to generate cash flow and repay loans rather than the value of assets pledged as security.
He also called for the introduction of more credit de-risking mechanisms to encourage lenders to extend financing to viable businesses that may lack traditional forms of collateral.
📰 Source: Kenyans.co.ke
Related Articles